

Cash Transfers and Debt in Andhra Pradesh’s Tribal Areas
Diego Maiorano, Chakradhar Buddha, Upasak Das
19 October 2026Summary
Cash transfers have become one of the main instruments of social policy in India. Drawing on a survey of 1,181 households in the tribal areas of Andhra Pradesh, this paper examines how two of the state’s largest schemes, Rythu Bharosa and Jagananna Amma Vodi, have shaped the debt relations of those who received them. Households receiving both transfers borrow at less than half the rate of households receiving neither, and borrowers credit the money with helping them service their loans. Yet most remain indebted, and moneylenders remain by far the main source of credit. Widening formal credit and resolving land record problems would strengthen what the transfers achieve.
Introduction
Following a national and international trend, cash transfers have become one of the main instruments through which governments in India offer assistance to the poor. These include national-level initiatives (such as the Pradhan Mantri Kisan Samman Nidhi Scheme [PM-KISAN], launched in February 2019),[1] as well as state-level ones, introduced in recent years by at least 17 governments. Collectively, they reach hundreds of millions of citizens, with a total expenditure exceeding S$38 billion.[2]
The popularity of cash transfers can be attributed to several factors. Rather than deciding on behalf of poor people what their needs are, governments can simply deliver cash and let recipients follow their own preferences. Implementation is relatively simple where a capillary infrastructure for delivering money directly to households already exists, and it cuts out intermediaries. Finally, cash transfers tend to be popular with voters and support local demand. Of course, exclusion remains an issue and our own research shows that the most vulnerable citizens – who are precisely those who most need the state’s support – are often unable to overcome technical or bureaucratic hurdles. However, they undoubtedly constitute an important source of income for a very large section of the population, particularly in rural areas.
Cash Transfers in Andhra Pradesh
The Andhra Pradesh (AP) government has been among the most active in this respect. The Yuvajana Sramika Rythu (YSR) Congress government, elected in 2019, implemented an ambitious welfare agenda known as Navaratnalu (Nine Gems), centred on cash transfers and covering areas such as housing, pensions, healthcare, education and financial assistance to farmers and other categories of people. Since 2019 the state has spent over ₹2 lakh crore (S$26 billion) on welfare (part of which on cash transfer schemes).
We studied two of these schemes. The YSR Rythu Bharosa (RB), launched in October 2019, aims at augmenting the income of landowning families and of Scheduled Caste, Scheduled Tribe, Backward Class and minority landless tenant families. It provides ₹13,500 (S$178) per year per family, irrespective of the size of the landholding. For families covered by PM-KISAN, the state pays the difference between the central allowance of ₹6,000 (S$79) and the RB allowance; for those excluded from PM-KISAN, such as landless tenants and forest land patta holders, the state pays the entire sum. Apart from a few exclusion criteria, such as being an income taxpayer or a state employee, the scheme is virtually universal, particularly in the area where we worked, where over 90 per cent of Adivasi households’ own revenue or forest land.
The Jagananna Amma Vodi (AMV) scheme, also introduced in 2019, provides ₹15,000 (S$198) per household per year to each mother, or other legal guardian, who holds a below poverty line (BPL) ration card and has at least one child attending school, irrespective of the number of children. Families are free to spend the money as they please, the only condition being 75 per cent of school attendance. In our fieldwork location, virtually all households hold a BPL ration card, so this scheme too is close to universal. In both cases, the money is transferred directly into the beneficiary’s bank account. Considering that a household is considered BPL in the state if its annual income is below ₹120,000 (S$1,600) in rural areas, these two schemes together represent a substantial addition to household income.
The Study
In December 2022, we surveyed 1,181 households across 12 mandals, 171 gram panchayats and 470 villages in the Paderu Integrated Tribal Development Agency (ITDA) region, which has a 90 per cent tribal population belonging to nine tribes, three of which are classified as particularly vulnerable tribal groups. Interviews were conducted at shandies, the weekly marketplaces where Adivasis gather in large numbers. We selected five shandies from each of the three administrative clusters of the ITDA, and enumerators stationed at the entry and exit points interviewed every fifth person encountered, with a minimum of 75 respondents per shandy. The survey was complemented by 77 semi-structured interviews covering, among other topics, the household’s economic condition, education, indebtedness, migration and health. It should be noted that those unable to attend the weekly shandies – disabled people, single women and the elderly – are often among the most vulnerable, so our sample might exclude those at the very bottom of the socio-economic ladder.
In an earlier paper,[3] we used this data to examine who was left out of the two schemes. We found large exclusion errors – 24 per cent among those eligible for RB and 15 per cent among those eligible for AMV – concentrated among the poorer and less educated households, and we traced them mainly to the administrative and technological steps required to enrol a beneficiary or to send a payment to their account. In this note we turn to the other side of the question: what the money did for those who received it, with a particular focus on debt. Of the households we surveyed, 372 received only RB transfer, 186 received only AMV transfer, 479 received both and 145 received neither.
How the Money was Used
Asked how they would prioritise spending if they had extra money, respondents named home repair most often as their first priority (31.9 per cent), followed by the repayment of loans (24.4 per cent), education (15.1 per cent), better food (7.5 per cent) and purchase of cattle (5.0 per cent). The items usually invoked in arguments about the misuse of cash by poor households barely appear: gold was named as a first priority by one per cent of respondents, a mobile phone by 1.8 per cent, and festivals and marriages by 0.25 per cent. Taking the first three priorities together, education was named by just over half of the respondents, home repair by two-thirds and the repayment of loans by about 40 per cent.
The pattern is consistent with the qualitative material we collected, and with evidence from other contexts, where the negative outcomes usually associated with cash transfers, such as increased alcohol consumption, are not substantiated by the data.[4] In our interviews, respondents described using the additional income to purchase higher quality seeds, to carry out land improvement works, to buy livestock and, in one case, a tractor; to purchase scooters used by household members for non-agricultural work; to buy material for school; and to meet health expenditure, which several households described as high or catastrophic. A few used the money to purchase health insurance. Many of our interviewees reported that their income had fallen over the previous years, mostly because of declining agricultural profitability, poor weather and the loss of soil fertility, and described the transfers as a way of offsetting that decline.
Many respondents named the repayment of loans as the first thing they would do with extra money and the proportion who actually reported doing so depended on what type of benefit they received: 47 of the 372 RB-only recipients (12.6 per cent), 24 of the 186 AMV-only recipients (12.9 per cent) and 93 of the 479 (19.4 per cent) who received both RB and AMV reported spending part of the cash received on repaying loans.
Borrowing
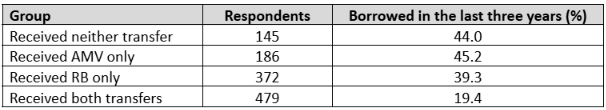
Respondents were then asked whether they had taken a loan in the previous three years.
Table 1: Incidence of borrowing by programme status
Source: Authors’ compilation.
Households that received both transfers borrowed at less than half the rate of households that received neither. While this is partly due to the fact that, as we showed in our earlier paper, beneficiaries are on average slightly better off than non-beneficiaries the key difference between those receiving both transfers and those receiving neither is the combined ₹28,500 (S$376) annual entitlement of the former group, which constitutes a significant amount in the context of tribal areas.
Repayment
Those who borrowed had considerable difficulty clearing their loans, also considering the very high interest rates (ranging between 12 and 36 per cent per year). Among RB-only borrowers, only 13 per cent had repaid in full; the figure was 27 per cent among AMV-only borrowers, 25 per cent among those receiving both transfers and 15.6 per cent among those receiving neither. Most borrowers in every group were therefore still carrying debt at the time of the survey.
Against this background, respondents credited the transfers with a substantial role in servicing their debts. Among RB-only borrowers, 72 per cent said the RB money had helped them repay their loans and 76 per cent said their loans had come down because of the scheme. Among those who received both transfers, 79.6 per cent said the money had helped them repay and 89 per cent said their loans had fallen. Across all recipients, 61 per cent of those with outstanding debts said they would not have been able to repay their loans had they not received the money.
These are perceptions rather than measurements, and respondents may be inclined to attribute improvements to a visible government programme. Still, the consistency across the three groups suggests that a good part of what the transfers do, from the point of view of the households themselves, is to keep existing debt obligations manageable.
Where the Credit Comes from
What the transfers do not appear to change is where households borrow. Moneylenders are, by a wide margin, the main source of credit for every group: 53.4 per cent of RB-only borrowers, 65.5 per cent of AMV-only borrowers, 59 per cent of those receiving both transfers and 58 per cent of those receiving neither named them their main source. Friends and family come second everywhere, at between 18 per cent and 28 per cent. Banks were the main source for 17.9 per cent of RB-only borrowers, and self-help groups for between nine per cent and 12 per cent of borrowers in the other groups. Households receiving both transfers are no more likely to borrow from a formal source than households receiving none.
Two explanations seem plausible. The first concerns land. As we documented in our earlier work, land records in the area are frequently out of date, in many cases still carrying the names of the present owners’ grandfathers, and mutations following a death or a sale are difficult and expensive to obtain (respondents reported costs ranging from ₹5,000 [S$66] to ₹10,000 [S$132] – a significant amount). LibTech India estimates that as many as 40 per cent of those excluded from RB are due to problems with the mutation of land records.[5] The same records that determine eligibility for a land-based transfer are also what would allow a farmer to offer land as collateral. A household whose records cannot establish its ownership is thus twice disadvantaged.
The second concerns the supply of credit to poor households more generally. Over the past decade, the government opened bank accounts for most citizens and linked them to Aadhaar and mobile numbers. This infrastructure works reasonably well for transferring money to households. However, it has not been matched by a comparable expansion in the availability of credit to those same households. AP has one of the densest networks of self-help groups in the country, and yet, in our sample, the main sources of borrowing remain either informal and exploitative, in the case of moneylenders, or informal and limited in what they can supply, in the case of family and friends.
Debt as Distress and Debt as Capacity
A high level of borrowing is not, in itself, evidence of hardship. Access to credit is in fact also a sign that a household is regarded as having some prospect of repayment. What distinguishes distress from capacity is the purpose of debts.
On that measure the difference between beneficiaries and non-beneficiaries is startling. Among households that received neither transfer, food expenditure was the reason for borrowing in 26.5 per cent of cases, the joint highest purpose alongside agricultural investment. Among RB-only borrowers, food accounted for 15.1 per cent, and among those receiving both transfers just for 9.9 per cent. In other words, not receiving cash transfers seems to be associated with distress borrowing.
Borrowing for education, by contrast, was reported by 9.6 per cent of RB-only borrowers, 17.9 per cent of AMV-only borrowers and 19.7 per cent of those receiving both, but does not appear among the main purposes reported by non-beneficiaries. Health expenditure accounted for 10.3 per cent of RB-only loans and 14.3 per cent of loans among those receiving both transfers.
Agricultural investment is the single most common purpose of borrowing, ranging from 21.7 per cent among those receiving both transfers to 32.9 per cent among RB-only borrowers. But households that received the transfers borrow for agriculture, for schooling and for health, while households that received nothing borrow, to a much greater extent, simply to eat.
Conclusions
The two schemes examined here deliver a substantial sum of money to households whose incomes are low and precarious. Our survey suggests that the money is used much as the schemes intend – for housing, cultivation, schooling and food – and that one of its most consistent uses is the servicing of debt. Recipients themselves say so: most borrowers reported that their loans had come down because of the transfers, and a majority said they could not have repaid without them. Households receiving both transfers borrow far less often than households receiving neither, and when beneficiaries do borrow, they borrow less often to cover food, which is a clear sign of distress.
The limits of what the transfers achieve are equally clear. Most borrowers in every group had not been able to repay in full, and the sources of credit are unchanged: roughly six in ten borrowers still rely on moneylenders, whose interest rates make debt a persistent drain on household finances. The transfers make the existing arrangement more bearable without altering it.
This suggests two directions for policy. The first is to widen the supply of formal credit in tribal areas, where bank accounts are now nearly universal but bank lending is not, and where the self-help group network appears to be meeting only a small share of borrowing needs. The second is to recognise that access to formal credit in these areas runs through the same administrative machinery that determines access to the transfers. Resolving the backlog of land record mutations would not only reduce the exclusion errors we documented in our earlier work; it would also restore to households the principal asset they could use to obtain credit on better terms.
. . . . .
Dr Diego Maiorano is Associate Professor at the University of Naples L’Orientale and Visiting Research Fellow at the Institute of South Asian Studies (ISAS), an autonomous research institute at the National University of Singapore (NUS). He can be contacted at dmaiorano@unior.it. Mr Chakradhar Buddha is with LibTech India and can be contacted at chakradhar@libtech.in. Dr Upasak Das is a Senior Lecturer at the Global Development Institute at the University of Manchester, United Kingdom. He can be contacted at upasak.das@manchester.ac.uk. The authors bear full responsibility for the facts cited and opinions expressed in this paper.
[1] “Pradhan Mantri Kisan Samman Nidhi Scheme”, Ministry of Agriculture & Farmers Welfare, India, 8 August 2026, https://www.pib.gov.in/PressReleaseIframePage.aspx?PRID=1946816®=48&lang=2.
[2] “India’s cash transfer boom gives relief to the poor but strains budgets”, BBC, 19 June 2026, https://www.bbc.com/news/articles/c0jy8zyn663o.
[3] Chakradhar Buddha, Upasak Das and Diego Maiorano, “Unfulfilled Promises – The Reality of Cash Transfers in Andhra Pradesh’s Tribal Areas”, Economic and Political Weekly, Vol. 60, No. 31, 2 August 2025, https://www.epw.in/journal/2025/31/special-articles/unfulfilled-promises.html.
[4] D K Evans and A Popova, “Cash Transfers and Temptation Goods”, Economic Development and Cultural Change, Vol. 65, No. 2 (2017): 189-221.
[5] Buddha, Das and Maiorano, op. cit.
Pic credit: File:Kalaigaon Tea Garden workers.jpg – Wikimedia Commons
-
 More From :
-
 Tags :
-
 Download PDF