

Summary
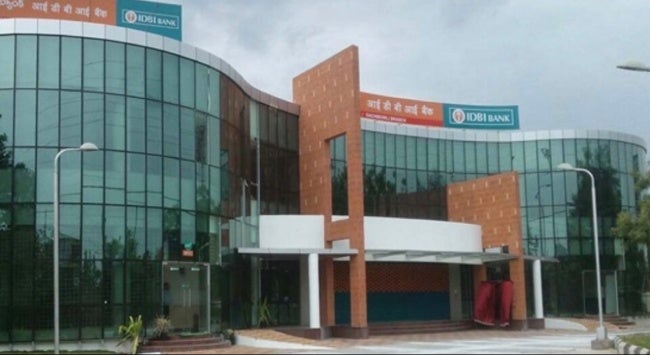
The Indian government has approved the privatisation of IDBI Bank through Fairfax Financial Holdings’ acquisition of a 60.72 per cent stake. This action is a culmination of a nine-year process. It heralds a new policy accommodation to encourage foreign direct investment into the banking sector with consequent advantages of commercial accountability, technology adoption and more professional management practices. This policy initiative could serve as a precursor for future banking reforms wherein the government transfers operational control, attract strategic capital and reduces its managerial responsibilities without necessarily having to dispose of its entire financial interest.
The Indian government and Life Insurance Corporation of India’s (LIC) decision to sell their 60.72 per cent stake in IDBI Bank to Fairfax Financial Holdings for ₹52,878.08 crore (S$7.13 billion) marks an important milestone in India’s financial-sector reforms. The transaction will transfer management control to a private strategic investor while the government and LIC will retain minority shareholdings of 15 per cent and 19 per cent, respectively.
The transaction represents the culmination of a nine-year process involving the bank’s financial distress, its rescue through LIC’s intervention, subsequent financial recovery and the government’s efforts to identify a suitable strategic investor. Its significance extends beyond disinvestment proceeds. It demonstrates the government’s willingness to transfer management control of a major banking institution to private ownership without requiring an immediate and complete withdrawal of public shareholding. It also establishes a potential precedent for further strategic disinvestment in India’s financial sector.
However, the transaction does not necessarily signal the immediate privatisation of other public-sector banks. IDBI Bank’s distinctive ownership history and regulatory classification make it a relatively unique case.
IDBI Bank: From Financial Distress to Privatisation
Established in 1964 as the Industrial Development Bank of India, IDBI Bank initially functioned as a development finance institution supporting industrial investment. In 2004, it was converted into a banking company and subsequently operated as IDBI Bank.
The transition exposed it to the challenges of commercial banking, including deposit mobilisation, retail lending, competition and credit-risk management. During the following decade, substantial exposure to corporate borrowers resulted in mounting non-performing assets and financial deterioration.
In 2017, the Reserve Bank of India (RBI) placed IDBI Bank under the Prompt Corrective Action (PCA) framework because of weaknesses in asset quality, profitability and capital adequacy. Its net non-performing asset ratio reached approximately 13 per cent by September 2018, reflecting the seriousness of its financial difficulties.
In January 2019, LIC acquired a controlling stake of approximately 49.24 per cent while the government retained 45.48 per cent. The RBI subsequently classified IDBI Bank as a private-sector bank for regulatory purposes from 21 January 2019, notwithstanding the substantial government and LIC ownership. This classification was crucial because it enabled the eventual transaction to proceed under the regulatory framework applicable to private-sector banks. The RBI removed IDBI Bank from the PCA framework in March 2021 following improvements in its financial position. Its recovery made it more attractive to potential investors.
Thus, the government first stabilised the institution through LIC’s intervention and subsequently sought to transfer management control to a private strategic investor.
A Nine-year Long Process
Three major factors explain the prolonged process.
First, banking is a highly regulated activity involving public deposits and financial stability. Potential investors had to satisfy the RBI’s fit-and-proper requirements and other regulatory and security clearances.
Second, there were differences between the government’s valuation expectations and investors’ willingness to pay. Financial bids received in February 2026 from Fairfax and Emirates NBD did not initially meet the government’s reserve-price expectations. The process was subsequently revisited and revised bids followed in July 2026.
Third, the transaction involved considerable ownership and regulatory complexities. It required the transfer of management control, determination of residual government and LIC shareholding, protection of minority shareholders and resolution of the regulatory implications of the successful bidder’s existing investments.
Consequently, the transaction involved considerably more than simply identifying a buyer and agreeing on a price.
The Fairfax Transaction and its Important Conditions
Under the approved arrangement, Fairfax will acquire 60.72 per cent of IDBI Bank and assume management control. The government will retain 15 per cent, LIC 19 per cent and other shareholders will hold the balance. Although the government and LIC will collectively retain 34 per cent, they will withdraw their nominees from the bank’s Board and cease exercising management control. Several important conditions accompany the transaction:
Five-year Lock-in: Fairfax will be subject to a five-year lock-in on its investment, ensuring its commitment to the bank’s long-term development rather than permitting an immediate exit.
Reduction of Shareholding to 26 per cent: Fairfax will be required to reduce its ownership to 26 per cent over the prescribed 15-year period, subject to applicable RBI requirements. This provides sufficient time for the investor to undertake restructuring while progressively complying with promoter-ownership norms.
Resolution of Existing Investment in CSB Bank: Fairfax already holds approximately 40 per cent in the Kerala-based CSB Bank. To address the regulatory implications of controlling interests in two Indian banks, Fairfax will be required, within two years of the share purchase agreement, to either merge CSB Bank with IDBI Bank or exit its holding in CSB Bank, subject to regulatory approval.
Retention of the IDBI Bank Brand: The buyer must retain the IDBI Bank name and brand for at least three years, providing continuity for customers and employees.
Protection of Employees and Pensioners: Existing employee service conditions and pension benefits are to be protected under the transaction arrangements.
Expansion into Financial Services: Fairfax has proposed contributing its interests in Go Digit Life Insurance, Go Digit General Insurance and IIFL Capital Services to IDBI Bank. Subject to necessary approvals, this could transform IDBI Bank into a broader financial-services group covering banking, insurance, investment banking and wealth management.
Policy Relaxations and Regulatory Accommodations
The most important aspect of the transaction is the way the government has reconciled its disinvestment objectives with the RBI’s prudential regulatory framework.
1. Classification as a Private-Sector Bank
The RBI’s classification of IDBI Bank as a private-sector bank in January 2019 was fundamental to the transaction. Although the government and LIC continued to hold substantial equity, the bank could be dealt with under the foreign investment framework applicable to private-sector banks rather than the more restrictive framework governing public-sector banks.
This distinction facilitated the participation of a foreign strategic investor and enabled the transfer of management control.
2. Flexibility in Promoter Shareholding Requirements
The most significant regulatory accommodation concerns the requirement that promoters of private-sector banks progressively reduce their shareholding to 26 per cent. Instead of requiring Fairfax to reduce its stake immediately after acquiring control, the transaction provides for a five-year lock-in followed by a longer period for bringing its holding down to the prescribed level. This phased approach serves two objectives: It allows the strategic investor sufficient time to exercise management control, restructure operations and implement its business plan. It ensures eventual compliance with the RBI’s promoter-ownership requirements.
This should be understood as phased regulatory compliance rather than a permanent exemption from ownership restrictions.
3. Transfer of Management Control Without Complete Government Exit
The transaction introduces an important distinction between ownership and management control. The government and LIC will retain a combined 34 per cent equity stake but will withdraw their Board nominees. Fairfax will exercise management control despite the continuing public-sector financial interest. This arrangement demonstrates that the government need not sell its entire shareholding immediately to transfer operational responsibility to private management.
The government has also authorised the Alternative Mechanism to undertake the sale of its residual 15 per cent stake through the prescribed market process. LIC will independently manage its remaining investment in accordance with its internal procedures and regulatory obligations.
4. Entry of a Foreign Strategic Investor
The transaction demonstrates a greater willingness to accommodate foreign strategic capital in India’s banking sector. However, foreign ownership does not imply freedom from domestic regulation. Fairfax must satisfy the RBI’s fit-and-proper requirements and comply with applicable conditions concerning ownership, voting rights, governance and restructuring.
The policy approach therefore combines openness to foreign investment with continued domestic regulatory supervision.
5. Resolution of Overlapping Banking Interests
The requirement that Fairfax resolve its existing investment in CSB Bank within the prescribed period is another important regulatory consideration. Rather than preventing the transaction altogether, the regulatory framework provides a pathway for resolving the overlapping ownership issue through a merger or divestment, subject to approval. This reflects a practical approach to reconciling commercial investment objectives with prudential requirements.
Overall, the relaxations are not a blanket exemption from banking regulation. They represent transaction-specific accommodations and phased compliance arrangements intended to facilitate strategic disinvestment without compromising financial stability.
Does the Transaction Signal Privatisation of Other Public-Sector Banks?
The IDBI Bank transaction strengthens the case for further bank privatisation but does not establish that a comprehensive privatisation programme is imminent.
The government’s strategic-disinvestment policy announced in the Union Budget for 2021-22 had already identified public-sector banks and insurance companies as part of the broader reform agenda. It envisaged maintaining a minimum public-sector presence in strategic sectors while permitting other enterprises to be privatised, merged or restructured.
The Budget also proposed privatising two public-sector banks and one general insurance company during that financial year. IDBI Bank, therefore, represents the implementation of an existing policy direction rather than the introduction of an entirely new approach. Nevertheless, its experience differs considerably from that of conventional nationalised banks for the following three reasons:
First, IDBI Bank has been classified as a private-sector bank by the RBI since January 2019.
Second, LIC had already acquired a controlling interest and played an important role in the bank’s recovery.
Third, the institution had returned to financial stability and possessed an established customer base and branch network, making it more attractive to strategic investors. Privatising a conventional public-sector bank could involve different legislative requirements, ownership structures, employee-related considerations and political challenges.
The most important lesson is that the government can transfer management control without immediately disposing of its entire shareholding. This model of partial public ownership combined with private management could provide flexibility in future strategic-disinvestment exercises. However, the availability of credible investors, valuation expectations and the financial condition of individual banks will determine whether similar transactions are feasible.
The more likely implication is selective rather than wholesale privatisation.
Wider Implications for India’s Financial Sector
The transaction has several important implications.
Reduction in Fiscal Burden: The government has historically provided capital support to IDBI Bank. Transferring management control to a private investor is expected to reduce dependence on government capital and release public resources for other development priorities.
Improved Efficiency and Governance: Private ownership could introduce stronger commercial accountability, better credit appraisal, improved risk management, technology adoption and more professional management practices.
Greater Foreign Investment: The transaction demonstrates India’s willingness to attract international strategic investors into its banking sector, potentially bringing capital, expertise and global financial practices.
Integrated Financial Services: If Fairfax’s proposed contributions of insurance and investment-banking businesses receive regulatory approval, IDBI Bank could develop into a diversified financial-services institution. This may improve cross-selling opportunities and strengthen its market position.
Demonstration Effect: A successful transaction could encourage further strategic disinvestment in financial institutions. Conversely, difficulties in integration, valuation or regulatory compliance could discourage similar initiatives.
It needs to however be underscored that privatisation must not be judged merely by the proceeds generated. Its success must also be assessed through improvements in asset quality, profitability, customer service, financial inclusion and institutional resilience.
Risks and Unresolved Issues
Despite the significance of the government’s approval, several issues require attention.
First, the transaction remains subject to completion of the necessary regulatory and legal formalities.
Second, the valuation of S$7.13 billion must be assessed against the bank’s market value, future earnings potential and the interests of public shareholders.
Third, Fairfax’s existing investment in CSB Bank must be resolved within the stipulated period.
Fourth, the proposed integration of insurance and investment-banking businesses requires regulatory approval and careful management of operational risks.
Fifth, the future sale of the government’s residual 15 per cent holding will determine the eventual ownership structure.
There are also broader public-interest concerns. Private management must balance commercial profitability with financial inclusion, priority-sector lending, employee welfare and responsible credit expansion. The RBI’s independence and supervisory authority will therefore remain essential to ensuring that commercial considerations do not undermine banking stability.
A Precedent, Not Yet a Blueprint for Wholesale Privatisation
The Fairfax acquisition marks the culmination of a lengthy process that began with IDBI Bank’s financial distress, continued through LIC’s intervention and recovery and eventually resulted in the government’s strategic-disinvestment initiative.
By this decision, the government has demonstrated its willingness to transfer management control of a major banking institution to a private strategic investor while retaining a minority financial interest. The transaction employs phased ownership reduction, regulatory accommodations and specific safeguards to reconcile commercial objectives with banking regulations. However, IDBI Bank’s distinctive regulatory classification, ownership history and financial recovery mean that its experience cannot automatically be replicated across other public-sector banks. The larger policy lesson is that government ownership of commercial banking institutions need not be permanent. Where a credible strategic investor is available and public interest can be protected, private management may offer an alternative to continued government control.
Ultimately, the success of this experiment will depend on whether IDBI Bank becomes more efficient, financially sustainable and competitive while continuing to fulfil its responsibilities towards customers and the wider economy.
Central Policy Takeaway
The most important point emerging from the article is that the IDBI Bank transaction represents a shift from government ownership and management to private management with residual government ownership.
This is significant because it provides a possible middle path for future banking reforms viz the government can transfer operational control, attract strategic capital and reduce its managerial responsibilities without necessarily having to dispose of its entire financial interest immediately.
The success of this model will determine whether it becomes a precedent for selective privatisation of other public-sector financial institutions.
. . . . .
Mr Vinod Rai is an Honorary Senior Fellow at the Institute of South Asian Studies (ISAS), an autonomous research institute at the National University of Singapore (NUS). He is also a former Comptroller and Auditor General of India. He can be contacted at raivinod@hotmail.com. The author bears full responsibility for the facts cited and opinions expressed in this paper.
Pic Credit: Wikimedia
-
 More From :
-
 Tags :
-
 Download PDF